Tax Evasion: Risks, Penalties & Compliance Guide for 2026
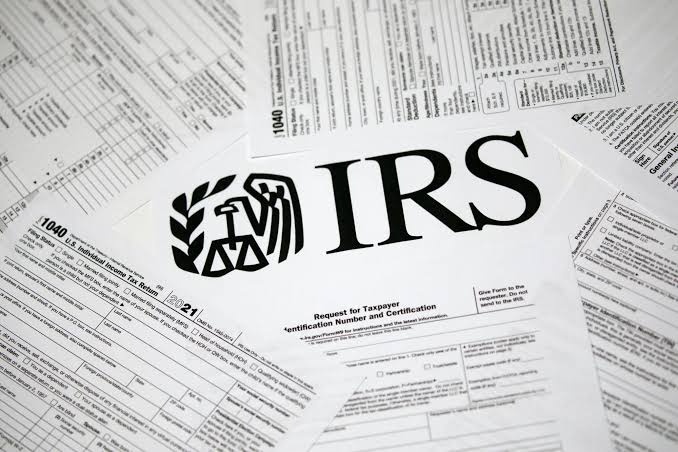
Tax compliance is an important part of responsible financial management for individuals and businesses. With electronic filing, digital payment systems, and increasingly detailed financial reporting, taxpayers have more opportunities to organize their records and meet their obligations accurately. At the same time, mistakes or deliberate misstatements can create significant financial and legal problems.
Understanding the difference between legitimate tax planning, an accidental error, and unlawful conduct is essential. Individuals who recognize potential compliance issues early can often take appropriate steps to address them before a relatively manageable problem becomes more complicated.
Understanding Tax Evasion
Tax evasion generally refers to the intentional and unlawful avoidance of taxes that a person or business legally owes. It can involve deliberately concealing income, falsifying records, claiming deductions that are not legitimate, or taking other deceptive steps to reduce tax liability.
The element of intent is important. Tax laws can be complicated, and taxpayers sometimes make genuine mistakes. An accidental calculation error is not automatically equivalent to deliberately providing false information.
Understanding this distinction can help taxpayers respond appropriately when questions arise about a return or financial transaction.
Common Forms of Unlawful Tax Conduct
Intentional tax misconduct can take several forms. Examples may include deliberately failing to report income, creating false business expenses, concealing financial assets, or submitting inaccurate information to obtain an improper tax benefit.
Businesses can face additional risks because their tax reporting may involve payroll, contractors, inventory, revenue, depreciation, and operating expenses.
Regardless of the circumstances, knowingly providing false information can create serious consequences.
Legitimate Tax Planning Is Different
Tax planning is a normal part of financial management. Individuals and businesses can generally use deductions, credits, retirement strategies, business structures, and other tax provisions permitted by law.
The distinction lies in whether the strategy follows applicable requirements. Legitimate planning works within the tax rules, while unlawful conduct involves intentional deception or concealment.
Taxpayers should be cautious about schemes promising extraordinary tax savings without clearly explaining the legal basis for those savings.
Why Accurate Records Matter
Maintaining organized records is one of the most effective ways to support tax compliance. Taxpayers should retain documentation relating to income, expenses, investments, property, business transactions, and other relevant financial activity.
Useful records may include:
- Wage and income statements
- Bank and investment statements
- Business invoices and receipts
- Property records
- Retirement account documents
- Payroll information
- Documentation supporting deductions and credits
Accurate records make filing easier and provide supporting evidence if tax authorities ask questions about reported information.
Digital Finance Is Changing Tax Compliance
Digital financial activity has become an important part of modern tax planning. Online businesses, electronic payment platforms, cryptocurrency, investment applications, and digital marketplaces can generate significant financial records.
Taxpayers should carefully track transactions conducted through these platforms and understand their reporting responsibilities.
Assuming that digital income is invisible to tax authorities can create unnecessary risk. Maintaining accurate electronic records is increasingly important in 2026.
Potential Civil Consequences
Tax violations can result in financial consequences even when a matter does not lead to criminal prosecution. Depending on the circumstances, a taxpayer may owe additional tax, interest, and civil penalties.
The consequences can vary based on factors such as the amount involved, the nature of the conduct, and whether the taxpayer acted intentionally.
Ignoring correspondence from tax authorities can make a financial issue more difficult to resolve. Promptly reviewing the underlying problem can help determine the appropriate response.
Criminal Consequences May Apply
Certain intentional violations can potentially result in criminal investigation or prosecution. Federal law establishes criminal penalties for specific forms of willful tax misconduct.
Depending on the circumstances, consequences can include substantial fines and imprisonment. The applicable penalties depend on the specific conduct and governing law.
Anyone facing a serious tax investigation should consider obtaining qualified legal advice before making significant decisions about their response.
What If You Discover an Error?
Finding an error on a tax return does not necessarily mean that unlawful conduct occurred. Taxpayers can make mistakes because of incomplete records, calculation errors, or misunderstandings of complicated tax requirements.
Depending on the circumstances, an amended return or another corrective procedure may be appropriate.
Taxpayers should avoid attempting to hide an existing mistake by creating additional false records or submitting misleading information. Addressing the issue accurately can help prevent additional complications.
Businesses Should Strengthen Internal Controls
Businesses can reduce compliance risks through strong financial procedures. Regular bookkeeping, separate business and personal accounts, documented expenses, and periodic financial reviews can all contribute to more accurate reporting.
Business owners should also ensure that employees responsible for financial records understand the importance of accurate documentation.
For businesses with complicated operations, professional accounting and legal advice can provide additional support.
Professional Guidance Can Be Valuable
Tax matters can become particularly complicated when they involve multiple years, businesses, significant investments, real estate, international transactions, or substantial tax liabilities.
A qualified tax professional or attorney can review the circumstances and explain potential obligations and lawful options.
Professional assistance can also help taxpayers distinguish between legitimate tax planning opportunities and strategies that may expose them to unnecessary legal risk.
Proactive Planning for 2026
Tax planning should not be limited to the weeks before a filing deadline. Reviewing income, expenses, investments, property transactions, and business activity throughout the year can help identify potential issues early.
Technology can make this process easier through accounting software, electronic recordkeeping, and secure document management. However, taxpayers should still review important information carefully before submitting returns.
Proactive planning can improve accuracy while helping individuals and businesses make better financial decisions.
Building a Culture of Compliance
For businesses and families alike, tax compliance is easier when accurate financial practices become part of everyday financial management.
Maintaining reliable records, communicating with financial professionals, reviewing documents, and addressing questions promptly can reduce uncertainty.
A culture of transparency also helps prevent small administrative mistakes from developing into larger financial problems.
Conclusion
Understanding tax evasion is important for anyone responsible for managing tax obligations. Intentional efforts to conceal income, falsify records, or avoid legally required taxes can result in serious financial and legal consequences.
The strongest approach is proactive compliance. Accurate records, legitimate tax planning, regular financial reviews, and timely professional guidance can help taxpayers navigate changing requirements while protecting their long-term financial interests.
In 2026, responsible tax management is not simply about filing a return on time. It is about maintaining accurate information, understanding financial responsibilities, and making informed decisions throughout the year.
About Premium Author
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.
Popular Categories
Stay Connected
Recent Posts